 Pre-approval funnel
A pre-approval funnel for buyers who are ready this month
Some buyers already have an agent and a weekend of showings booked. They need a pre-approval letter, not a newsletter. This funnel gets them to the documents and the call fast.
Included in every plan · or add to any plan for $59/mo
Question 1 of 4
What price range are you shopping?
Question 2 of 4
How do you earn most of your income?
Question 3 of 4
Do you have an agent yet?
What it is
What is a pre-approval funnel?
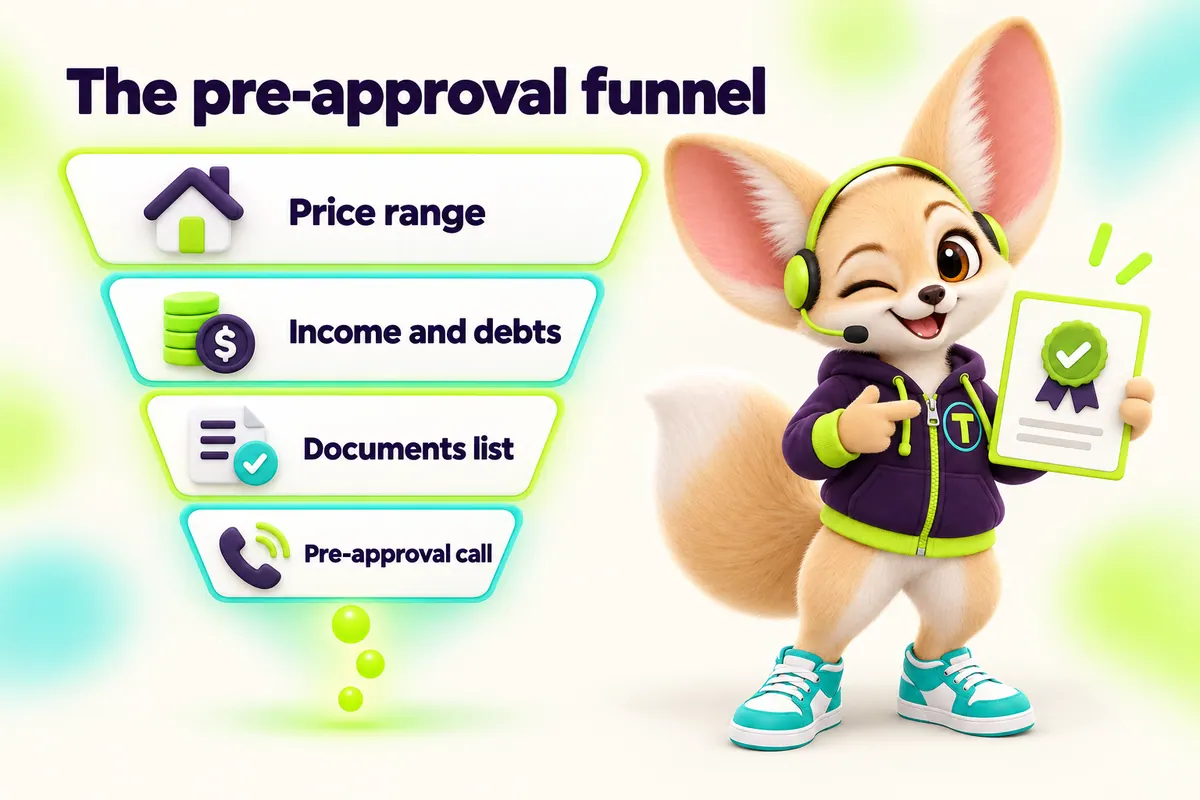
A pre-approval funnel is a short landing page and form for buyers who are ready to shop. It collects price range, income type and debts, shows a documents checklist, and books a pre-approval call or starts the full application — with a fast handoff so buyers can make offers quickly.
Who it's for
Buyers actively shopping or about to, often referred by a real estate agent, who need a pre-approval to make offers.
What makes them search
- Agent asked for a pre-approval letter
- Found a house they love
- Open house visit
- Lease ending soon
The funnel map
How the Pre-approval funnel moves a borrower
- 01
Ad or link
Ad angle 1 of 2
Shopping this month? Get your pre-approval started tonight
- 02
Landing page
One screen, one promise
A pre-approval funnel is a short landing page and form for buyers who are ready to shop.
- 03
4-question quiz
Tap-only answers
What price range are you shopping? · How do you earn most of your income? · Do you have an agent yet? · When do you want to make an offer?
- 04
Result page
Next step, no promises
The result page shows a documents checklist tailored to the income type, explains the difference between pre-qualification and pre-approval, and offers two buttons: start the application now or book a 15-minute call.
- 05
Handoff & follow-up
4 touches written for you
Straight into the 1003-style application, pre-filled. Agent name, if given, is attached to the CRM contact for updates (with the buyer's permission).
The questions, word for word
Four taps. No paperwork yet.
This is the quiz we write for you (your edits welcome). Every answer is a button, so it works one-handed on a phone.
Question 1
What price range are you shopping?
- Under $300k
- $300k–$500k
- $500k–$800k
- Over $800k
Question 2
How do you earn most of your income?
- W-2 salary
- Hourly
- Self-employed
- Retirement / other
Question 3
Do you have an agent yet?
- Yes
- Not yet
- Need a recommendation
Question 4
When do you want to make an offer?
- This week
- This month
- In 1–3 months
Result page
What the borrower sees next
The result page shows a documents checklist tailored to the income type, explains the difference between pre-qualification and pre-approval, and offers two buttons: start the application now or book a 15-minute call.
Follow-up, written for you
What happens after they tap "done"
The follow-up below runs from the CRM included with your site. Texts only go to borrowers who ticked the SMS consent box. Messages are sample copy — we tailor them to your voice.
- 0–30 secondsSMS
{first}, {LO} here — let's get your pre-approval moving. Start here: {apply} or pick a call time: {calendar}. Reply STOP to opt out.
- 1 minuteEmail
Documents checklist for {income type} + application link.
- 20 minutes (no application)Call
LO call attempt; buyers making offers this week get priority.
- Day 1SMS
Any questions about the documents? Snap a photo of anything confusing and I'll explain.
Ads & compliance
Ad angles that work — and stay compliant
Sample ad angle
"Shopping this month? Get your pre-approval started tonight"
Urgency without promises.
Sample ad angle
Agent co-branded page: "Get pre-approved with [Agent]'s trusted lender"
RESPA Section 8: no payments for referrals; co-marketing must be paid at fair value.
Compliance built in
- "Pre-approval" wording matches what the LO actually issues; no "guaranteed approval".
- Agent co-branding follows RESPA Section 8 — no referral fees, co-marketing at fair value, reviewed by compliance.
- NMLS ID, state licence lines and Equal Housing Opportunity visible.
- Sensitive documents requested only through secure channels after contact.
We explain public rules; we don't give legal advice. Your compliance team approves every funnel before launch. Mortgage ad compliance, explained.
What we watch
Numbers that tell us it's working
- 1Applications started
- 2Time to pre-approval letter
- 3Agent-referred share
- 4Offers made within 30 days
On Funnel Stack and Full Library we test one or two changes a month (a headline, a question order) and report what moved.
Included with this funnel
- Landing page, 4-question quiz and result page, written and built
- Application handoff, pre-filled from the quiz
- 4-touch follow-up in the CRM (SMS with consent, email, tasks)
- 2 ad angles written to avoid unbalanced trigger terms
- Schema, FAQs and your NMLS / Equal Housing block on every page
Not included
- Ad spend (paid to Meta or Google from your account)
- Legal or compliance approval (your compliance team)
- Loan decisions — those stay with you
FAQ
Pre-approval funnel questions
Specific to the pre-approval funnel. General questions live on the FAQ page.
Can't find it? Search every answer or ask the funnel desk.
What is the difference between pre-qualification and pre-approval?
Pre-qualification is an early estimate based on what the borrower tells you. Pre-approval usually involves a credit check and documentation review, so it carries more weight with sellers. Lenders define the terms differently; the funnel uses the wording your company uses.
Can real estate agents co-brand the funnel?
Yes, as a co-branded landing page. Under RESPA Section 8, nothing of value can be exchanged for referrals, and co-marketing costs must be shared at fair market value. We build the page; your compliance team approves the arrangement.
Why are there only four questions before the application?
Ready buyers want speed. Four questions tailor the documents checklist, then the application opens pre-filled. Long forms on the first screen lose people who are on their phone between showings.
Does the funnel collect Social Security numbers?
Not on the landing page. Sensitive data is collected only in the secure application step or by the LO's loan origination system, never in an open quiz or a text message.
How does the agent get updates?
If the buyer names an agent and agrees, the CRM can send the agent milestone notes (application started, pre-approval issued) without sharing private financial details.
What documents are usually on the checklist?
Typically recent pay stubs, W-2s or tax returns, bank statements and ID — tailored by income type. Self-employed buyers see the bank statement funnel's list instead. Your LO edits the list to match your company's requirements.
Can I use this funnel at open houses?
Yes. We create a QR code poster that opens the funnel with the open-house address attached, so the LO knows which listing the buyer saw.
What makes this different from a website contact form?
A contact form asks "how can we help?" and waits. This funnel qualifies, tailors a checklist, opens the application and texts the buyer within seconds — the same visitor, a much faster path to a letter.
No question matches that.
Try fewer words, pick "All", or send us the question — we answer within one business day.
Next stage: booked
Launch the pre-approval funnel in about two weeks
Book a call and we'll review your programs, traffic sources and compliance requirements, then send a written plan for this funnel.
Free 25-minute call · month-to-month plans · no ad spend required to start