 First-time buyer & FHA funnel
A first-time homebuyer funnel that turns renters into calls
Renters do not search for "FHA loan" first. They search "can I afford to buy". This funnel starts there, answers it in four taps, and books the pre-approval call while they are still curious.
Included in every plan · or add to any plan for $59/mo
Question 1 of 4
When are you hoping to buy?
Question 2 of 4
What do you pay in rent today?
Question 3 of 4
Have you saved toward a down payment?
What it is
What is a first-time buyer & fha funnel?
A first-time homebuyer funnel is a short landing page and quiz that asks renters about timing, budget and savings, shows them a sensible next step (often an FHA or low-down-payment conversation), and books a pre-approval call with a licensed loan officer — with an instant text so the lead never waits.
Who it's for
Renters aged roughly late 20s to early 40s, often with modest savings, who have never owned. NAR's 2025 Profile of Home Buyers and Sellers (released November 2025) put first-time buyers at 21% of purchases with a median age of 40 — a smaller, older, more cautious group than a decade ago, which is why the funnel leads with reassurance, not rates.
What makes them search
- Lease renewal notice
- Rent increase
- A friend just bought
- A new baby or job
The funnel map
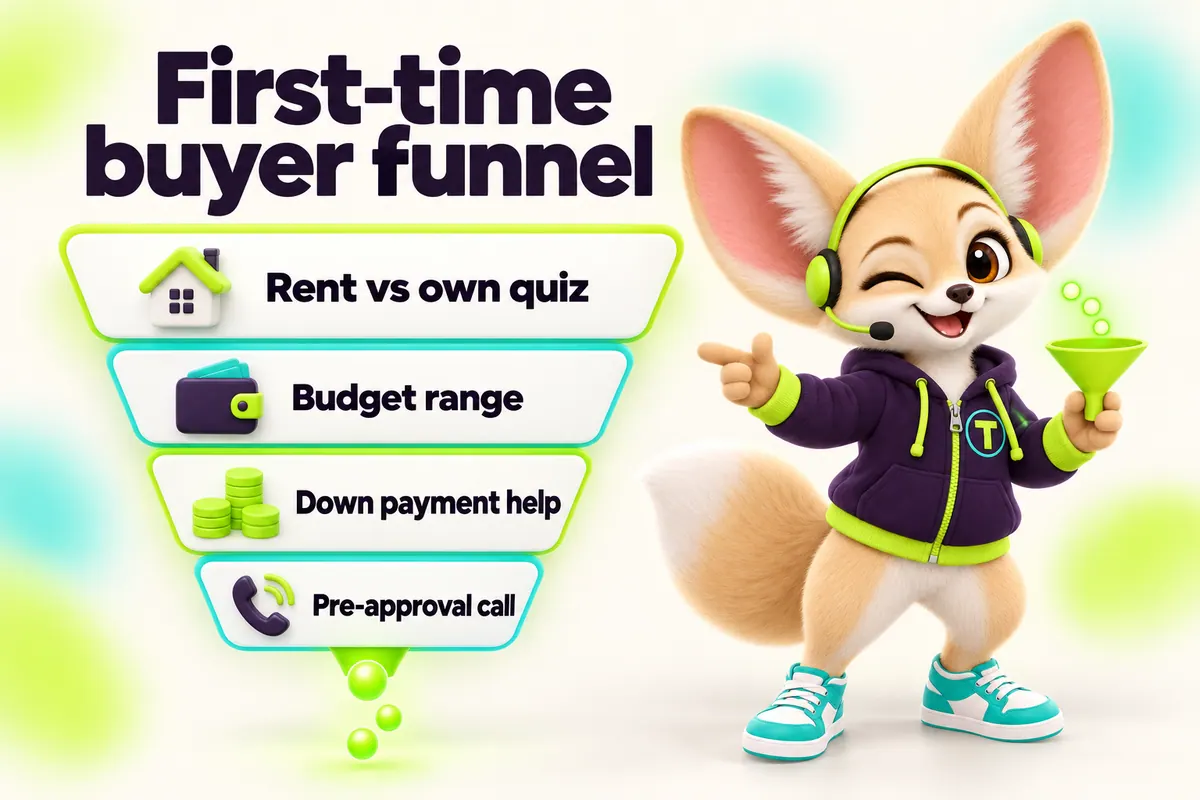
How the First-time buyer & FHA funnel moves a borrower
- 01
Ad or link
Ad angle 1 of 3
See what a monthly payment could look like — 4 questions
- 02
Landing page
One screen, one promise
A first-time homebuyer funnel is a short landing page and quiz that asks renters about timing, budget and savings, shows them a sensible next step (often an FHA or low-down-payment conversation), and books a pre-approval call with a licensed loan officer — with an instant text so the lead never waits..
- 03
4-question quiz
Tap-only answers
When are you hoping to buy? · What do you pay in rent today? · Have you saved toward a down payment? · How would you describe your credit?
- 04
Result page
Next step, no promises
The result page names the likely conversation — "a low-down-payment option such as FHA may be worth discussing" — explains the next three steps in plain words and offers two buttons: book a 15-minute call or start the full application.
- 05
Handoff & follow-up
6 touches written for you
Answers pre-fill the 1003-style application so the borrower never types the same thing twice.
The questions, word for word
Four taps. No paperwork yet.
This is the quiz we write for you (your edits welcome). Every answer is a button, so it works one-handed on a phone.
Question 1
When are you hoping to buy?
- In the next 3 months
- 3–6 months
- 6–12 months
- Just exploring
Question 2
What do you pay in rent today?
- Under $1,500
- $1,500–$2,500
- Over $2,500
- I live with family
Question 3
Have you saved toward a down payment?
- Yes, a good start
- A little
- Not yet — need help
Question 4
How would you describe your credit?
- Strong
- Average
- Rebuilding
- Not sure
Result page
What the borrower sees next
The result page names the likely conversation — "a low-down-payment option such as FHA may be worth discussing" — explains the next three steps in plain words and offers two buttons: book a 15-minute call or start the full application.
Follow-up, written for you
What happens after they tap "done"
The follow-up below runs from the CRM included with your site. Texts only go to borrowers who ticked the SMS consent box. Messages are sample copy — we tailor them to your voice.
- 0–30 secondsSMS
Hi {first}, it's {LO} — thanks for checking your options. Want me to walk you through what first-time buyers in {city} usually do next? Pick a time: {calendar}. Reply STOP to opt out.
- 2 minutesEmail
"Your first-home checklist" — the 5 documents that make a pre-approval quick, plus your booking link.
- 1 hour (no booking)Task
Call task created for the LO with the quiz answers on the contact.
- Day 2SMS
Quick one: are you still thinking about the next 3–6 months, or later? Either is fine — I'll send the right info.
- Day 7Email
"Rent vs own: the questions to ask" — educational, no rates, links back to the calculator.
- Day 21Email
Down payment assistance overview for the LO's state (written with the LO, general and dated).
Ads & compliance
Ad angles that work — and stay compliant
Sample ad angle
"See what a monthly payment could look like — 4 questions"
Curiosity angle, no rate or payment figures in the ad, so no Reg Z trigger terms.
Sample ad angle
"Renting in [City]? Here's how first-time buyers start"
Location in copy only — Meta's housing/financial categories restrict ZIP and age targeting, not the words on the ad.
Sample ad angle
"Down payment help exists. Find out what you may qualify for"
Mention programs generally; never promise eligibility or amounts.
Compliance built in
- No rate, payment or down-payment percentage in ads unless the full Reg Z disclosure set appears with it.
- Equal Housing Opportunity text and the LO's NMLS ID on the landing page and result page.
- SMS sent only after an unticked, specific consent checkbox; STOP honoured automatically.
- FHA is an insurance program from HUD — copy never implies government endorsement of the LO.
We explain public rules; we don't give legal advice. Your compliance team approves every funnel before launch. Mortgage ad compliance, explained.
What we watch
Numbers that tell us it's working
- 1Quiz start rate (visitors who tap the first answer)
- 2Quiz completion rate
- 3Time from submit to first reply
- 4Booked-call rate
- 5Applications started from the result page
On Funnel Stack and Full Library we test one or two changes a month (a headline, a question order) and report what moved.
Included with this funnel
- Landing page, 4-question quiz and result page, written and built
- Application handoff, pre-filled from the quiz
- 6-touch follow-up in the CRM (SMS with consent, email, tasks)
- 3 ad angles written to avoid unbalanced trigger terms
- Schema, FAQs and your NMLS / Equal Housing block on every page
Not included
- Ad spend (paid to Meta or Google from your account)
- Legal or compliance approval (your compliance team)
- Loan decisions — those stay with you
FAQ
First-time buyer & FHA funnel questions
Specific to the first-time buyer & fha funnel. General questions live on the FAQ page.
Can't find it? Search every answer or ask the funnel desk.
Why start with a quiz instead of an application?
Because most renters are not ready to share income and Social Security details on the first visit. Four tap-only questions feel like help, not paperwork, so more people finish. The application is offered on the result page to those who are ready, pre-filled with what they already told you.
Does the funnel promise FHA approval or a down payment amount?
No. The result page says a low-down-payment option "may be worth discussing" and invites a call. Eligibility depends on the borrower's full file, so the copy never promises approval, a rate or an amount.
Can I mention down payment assistance programs?
Yes, in general terms. We write a short, dated overview with you for the programs you actually work with. We avoid naming amounts or guaranteeing eligibility, and we update the page when a program changes.
What is the minimum down payment on an FHA loan?
Under HUD's FHA handbook, borrowers with a credit score of 580 or higher can put down as little as 3.5%; scores from 500 to 579 generally need 10%. That is educational context for your page — the funnel itself does not advertise a percentage in ads.
How fast does the first text go out?
Seconds after the quiz is submitted, if the borrower ticked the SMS consent box. If they did not, the first touch is an email and a call task for you.
Will this work if I only do conventional loans?
Yes. The quiz is program-neutral; we change the result page to point at the options you offer, such as low-down-payment conventional programs.
Can I run this funnel without ads?
Yes. Many LOs link it from their website, email signature, open-house flyers (QR code) and social bios. Ads add volume; they are not required.
Is the funnel in Spanish too?
We can build a Spanish version as a second funnel on any plan. We write it natively rather than machine-translating, and the follow-up messages switch language to match.
What happens to leads who say "just exploring"?
They get a slower, educational email series and no calls until they reply or book. Pushing early-stage renters usually loses them; staying helpful keeps you first in line.
No question matches that.
Try fewer words, pick "All", or send us the question — we answer within one business day.
Next stage: booked
Launch the first-time buyer & fha funnel in about two weeks
Book a call and we'll review your programs, traffic sources and compliance requirements, then send a written plan for this funnel.
Free 25-minute call · month-to-month plans · no ad spend required to start